Insurance in India: A Practical Beginner Guide to Financial Protection
Learn how insurance works, including health, life, motor and property cover, important policy terms, claim steps, exclusions and practical tips for choosing protection.
Insurance is a financial protection arrangement. You pay a premium to an insurer, and the policy may provide a defined benefit or cover eligible losses when a covered event occurs. It cannot prevent every problem, but it can reduce the financial impact of major health, life, vehicle or property risks.
How insurance works
A policy is a contract that describes the covered risk, sum insured, premium, exclusions, waiting periods, deductibles and claim process. Read the policy wording and schedule carefully. A low premium is not useful if important risks are excluded or the coverage is too small.
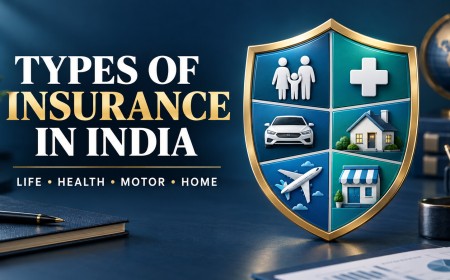
Major types of insurance
Health insurance
Health cover may help pay eligible hospitalisation or treatment costs according to the policy. Check room-rent limits, waiting periods, exclusions, network hospitals, co-pay and claim documentation.
Life insurance
Life insurance is designed to provide financial support to nominees after the insured person’s death, subject to policy terms. The required cover depends on income, dependants, liabilities and future responsibilities. Do not confuse pure protection with products designed for savings or investment.
Motor insurance
Motor policies can include legally required third-party cover and optional own-damage protection. Compare IDV, deductibles, add-ons, exclusions and the cashless repair network before renewal.
Home and property insurance
Property cover may protect a structure or contents against specified events. Check whether the sum insured reflects rebuilding or replacement costs and understand exclusions for wear, poor maintenance or unlisted items.
Important policy terms
- Premium: amount paid to keep the policy active.
- Sum insured: maximum cover or benefit stated by the policy.
- Deductible: amount the policyholder pays before eligible cover applies.
- Exclusion: a situation or expense the policy does not cover.
- Waiting period: time before selected conditions become claimable.
- Nominee: person recorded to receive a life-policy benefit, subject to law and policy terms.
- Renewal: continuing cover for a new policy period under applicable conditions.
How to choose suitable cover
- List the risks that could seriously affect your family or business.
- Check existing employer or government coverage first.
- Compare coverage, exclusions and claim conditions—not only premium.
- Choose a realistic sum insured based on future needs and inflation.
- Disclose health, occupation and other relevant information honestly.
- Buy through a regulated channel and save all policy documents.
Claims and claim settlement
Inform the insurer within the stated time, keep the policy number available and submit accurate documents. For cashless treatment or repairs, use the approved process. A claim can be delayed when details are incomplete, facts are withheld or the event is outside the cover. If a claim is rejected, ask for the written reason and use the insurer’s grievance process before escalating to the appropriate authority.
Common mistakes
- Buying a policy without reading exclusions.
- Underinsuring health, life or property because the premium looks cheaper.
- Allowing a policy to lapse without checking renewal options.
- Giving inaccurate information on the proposal form.
- Assuming every hospital, repair or illness is automatically covered.
- Paying an unknown person or sharing OTPs during a fake renewal call.
Frequently asked questions
Is insurance an investment?
Most insurance is primarily risk protection. Some products combine protection with savings or market-linked features, but their costs, returns and risks must be understood separately.
Should I buy the cheapest policy?
Not necessarily. Compare the protection offered, limits, exclusions, service process and financial suitability. The best policy is the one that addresses the risk you actually need to manage.
Can a claim always be guaranteed?
No. Claims are assessed according to the policy contract, documents and applicable rules. Honest disclosure and understanding the wording reduce avoidable disputes.
Final takeaway
Insurance works best when it is chosen for a clear protection need and reviewed as life circumstances change. Keep documents safe, pay premiums on time, disclose facts accurately and seek qualified advice for complex or high-value decisions.
Disclaimer: This article is for general educational information only and is not insurance, financial or legal advice. Policy terms and regulations can change; verify current details with the insurer and official sources.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Software developer with expertise in full-stack web development and financial market analysis, specializing in building tracking tools for trading metrics.
Comments (0)