What Is Investment? A Practical Beginner’s Guide to Building Wealth
Understand what investment means, how saving differs from investing, which options beginners may encounter in India, and how to plan around goals, risk, costs and time.
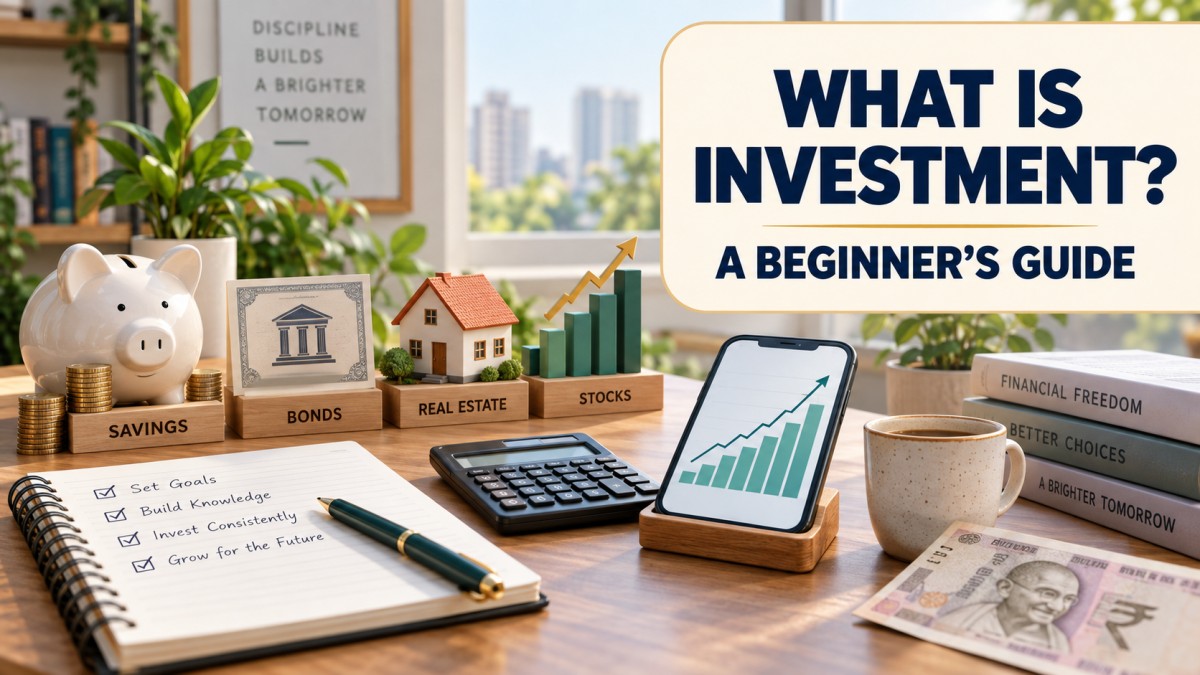
Most people hear the word investment and immediately think of stocks, mutual funds or a rising chart. The more useful starting point is simpler: investing means putting money into an asset or product with the hope that it will preserve value, generate income or grow over time. That outcome is possible, not guaranteed.
Investing is different from saving and different from trading. Savings usually focus on safety and near-term access. Trading focuses on buying and selling based on shorter-term price movement. Investing usually works over a longer period and requires a plan that matches your goals, time horizon and ability to handle losses.
This beginner-friendly guide explains how investment works, the main options available in India, the risks people often overlook and a sensible process for getting started. It is educational information, not a personalised recommendation.
What is investment?
Investment is the process of committing money to an asset, financial product or business with the expectation that it may provide a future benefit. The benefit may be interest, a dividend, rental income, business growth or an increase in value.
Every investment has a trade-off. A product that is easier to access and more stable may offer lower growth potential. An asset with greater growth potential may fall sharply or take a long time to recover. The right question is not “Which investment gives the highest return?” It is “Which level of risk and time commitment is suitable for this goal?”
Saving, investing and trading: the difference
| Approach | Main purpose | Typical time frame | Main concern |
|---|---|---|---|
| Saving | Safety and access to money | Short term | Inflation can reduce purchasing power |
| Investing | Long-term growth or income | Medium to long term | Market, credit and product risk |
| Trading | Profit from price movement | Short to medium term | Timing, costs and emotional decisions |
These approaches can exist together. Emergency money may stay in a suitable savings product, long-term goals may use a diversified investment plan, and some people may trade only with money they can genuinely afford to lose. They should not be mixed into one unclear account or one vague goal.
Why do people invest?
- To protect purchasing power: prices generally change over time, so money kept idle may buy less in the future.
- To fund a goal: education, a home, retirement, a business or another long-term need may require money beyond monthly income.
- To create potential growth: ownership of productive assets may grow over long periods, although the path is uncertain.
- To create income: some products may provide interest, dividends or other income, subject to their terms and risks.
Investment should serve a goal. A product purchased without knowing the time horizon can become difficult to hold when its value moves in the wrong direction.
Start with your financial foundation
Before choosing an investment, check the basics. Keep money for immediate expenses and build an emergency reserve appropriate to your household. Understand high-cost debt and make required payments on time. Review health and life protection needs where relevant. Investing money that may be needed next week can force you to sell at an unsuitable time.
Make a list of goals with an approximate amount and date. “Build wealth” is too broad to guide a decision. “Pay for a course in three years” and “retirement in twenty-five years” have different time horizons and may need different levels of stability.
Risk, return and time horizon
Risk is not only the chance that an asset price falls. It can also include a borrower failing to repay, an investment becoming difficult to sell, a platform or issuer facing trouble, fees reducing the outcome, currency movement, fraud and the risk that returns do not keep up with inflation.
Time can help an investor manage volatility, but it does not remove risk. A long-term label cannot make a poor-quality asset safe. Before investing, write down the maximum temporary fall you could tolerate without abandoning the plan and the conditions that would make you review the investment.
| Question | Why it matters |
|---|---|
| When will I need the money? | Short deadlines allow less time to recover from a fall. |
| Can I tolerate a temporary loss? | Price movement can test the plan before the goal arrives. |
| How easy is it to sell? | Some assets have lock-ins, exit charges or limited buyers. |
| What can I lose beyond price? | Debt, leverage, fraud and platform risk need separate attention. |
| What are the total costs? | Fees, taxes and spreads reduce the amount that compounds. |
Common investment options in India
Bank deposits and savings products
Savings accounts and fixed or recurring deposits are familiar options for money that needs relatively high stability and access according to the product terms. They still have inflation, interest-rate and institution-related considerations. Check current rates, premature-withdrawal rules and applicable protections directly with the bank.
Bonds and government securities
A bond represents a lending arrangement: an issuer borrows money and promises payments according to the terms. Government and corporate bonds do not carry identical risks. Credit quality, duration, interest-rate movement, liquidity and the possibility of selling below the purchase price all matter.
Mutual funds
A mutual fund pools money from investors and invests according to a stated mandate. The fund’s documents explain its objective, asset mix, risks, expenses and dealing process. Equity, debt, hybrid, index and other categories can behave very differently. A mutual fund is not automatically diversified or safe simply because it contains many securities.
Systematic Investment Plans
A SIP is a method of investing a fixed amount at regular intervals in a mutual-fund scheme. It can create discipline and spread purchases over time, but it does not guarantee profit and it does not eliminate market risk. The scheme, asset category, costs and time horizon still need to suit the goal.
Direct stocks
Buying a company’s shares means owning a small interest in that business. The price can be affected by earnings, debt, competition, management, the economy, market sentiment and many other factors. A company with a familiar product is not automatically a suitable investment. Read official filings and understand what you own rather than buying only because a price is rising.
Gold
Gold may play a role in some portfolios, but the form matters. Jewellery includes making charges and resale considerations. Market-linked gold products have their own costs, structures and risks. Gold does not produce business profits in the same way a productive company can, so it should be evaluated for its role rather than treated as a guaranteed hedge.
Real estate
Property can provide use, rent or potential appreciation, but it is illiquid and can require large capital, maintenance, taxes, financing and legal checks. A property purchase should be assessed separately from a small, easily traded financial investment.
Cryptocurrency and other speculative assets
Crypto assets can be highly volatile and may add custody, platform, technology, fraud and regulatory risks. If someone considers them at all, they should treat them as speculative, use only an amount they can afford to lose and verify current rules and platform terms. A token is not a replacement for an emergency fund or a diversified long-term plan.
How compounding works
Compounding means that returns, when retained and reinvested, can potentially contribute to future returns. The effect depends on time, the amount invested, the rate of return and the costs or taxes involved. Real markets do not deliver a fixed return every year, so compounding examples are illustrations rather than promises.
For example, adding a modest amount regularly for many years may build a larger balance than waiting for a “perfect” entry, but the result can still be higher or lower than an estimate. Avoid calculators that show one attractive number without explaining assumptions, volatility, fees and inflation.
How to build a simple investment plan
- Define the goal: write the purpose, target date and an approximate future amount.
- Protect the foundation: separate emergency money and required expenses from long-term capital.
- Choose a risk level: consider income stability, dependants, debt, time horizon and how you react to losses.
- Select a suitable category: understand what the product owns, how it earns money and when you can exit.
- Start at a sustainable amount: a plan that fits the monthly budget is easier to continue.
- Diversify thoughtfully: spread risk across suitable assets instead of buying many versions of the same risk.
- Review, do not constantly react: check progress and goal changes at a planned interval.
Diversification does not guarantee that a portfolio will not fall. It is intended to reduce dependence on one asset, company, sector or outcome.
Fees, taxes and paperwork
Look beyond the headline return. Depending on the product, costs may include management expenses, brokerage, commissions, spreads, exit charges, account fees, stamp duty or taxes. A small annual cost can matter over a long period because money used for costs cannot compound for the investor.
Keep statements, contract notes, purchase details, redemption records and bank entries. Tax treatment depends on the product, transaction and rules in force at the time. Check current information through the Income Tax Department and consult a qualified tax professional for a complex portfolio or large transaction.
Direct plan, regular plan and advice
Some investment products offer different routes or plans with different costs and service arrangements. Read the official product documents and understand whether you are paying for distribution, advice, execution or another service. “Direct” does not mean risk-free, and “regular” does not automatically mean unsuitable.
If you use an adviser, check the person’s identity, regulatory status where applicable, fees, conflicts and the exact service being offered. Never hand over account passwords, OTPs or private keys. A legitimate professional should not need control of your personal banking credentials.
Common mistakes beginners make
- Chasing guaranteed returns: a guaranteed high return with no risk is a warning sign.
- Investing without an emergency buffer: an unexpected bill can force a bad withdrawal.
- Buying because of a tip: a message or influencer video is not research.
- Ignoring concentration: several funds can still own many of the same companies.
- Using leverage: borrowed exposure can magnify losses and create forced exits.
- Stopping after a fall: selling in fear can turn a temporary movement into a permanent loss.
- Ignoring costs: fees and taxes change the net result.
- Checking prices every hour: short-term noise can overwhelm a long-term plan.
How to avoid investment scams
Scammers often use urgency, fake screenshots, celebrity names, private groups and promises of fixed daily income. Be careful when someone asks you to deposit money to unlock a withdrawal, share your screen, install remote-access software or send a recovery fee.
Verify the website and contact details independently. Do not trust a certificate, logo or social-media follower count as proof. Never share a one-time password, card PIN, trading password, recovery phrase or private key. If the opportunity cannot be explained clearly and checked through reliable sources, walking away is a sensible financial decision.
A beginner’s 30-day learning plan
- Days 1–7: list goals, income, expenses, debt and emergency needs. Learn the difference between saving, investing and trading.
- Days 8–14: compare a few asset categories and read official product documents instead of relying only on summaries.
- Days 15–21: write a simple investment policy: goal, time horizon, amount, risk limit, review date and exit conditions.
- Days 22–30: verify the account, fees and paperwork. Start only if the decision still fits your plan after the initial excitement has passed.
Frequently asked questions
How much money do I need to start investing?
There is no universal minimum that makes an investment suitable. Begin only with money that is not needed for essential expenses or emergencies. The amount should fit the product’s minimum, costs and your monthly budget.
Is investing safe?
No investment is completely risk-free. Safety depends on the product and the risk being considered—price movement, credit, liquidity, fraud, inflation and access can all be different.
Is a SIP guaranteed to make money?
No. A SIP is a regular investment method, not a guarantee. The underlying scheme can rise or fall, and the final result depends on the asset category, costs, time and market conditions.
Should beginners buy stocks directly?
Only after learning how to assess a business, valuation, financial statements and risk. A diversified product may be easier for some beginners, but it also has its own risks and costs. There is no single correct choice for everyone.
What is the difference between a mutual fund and a stock?
A stock is a direct ownership interest in one company. A mutual fund pools money and follows its stated investment mandate, which may provide exposure to multiple securities. The fund’s concentration, category and costs still need review.
How often should I review investments?
Review at a planned interval and when your goal, income or risk capacity changes. Constantly reacting to daily price movement can turn a long-term plan into short-term trading.
Can I invest while I have a loan?
It depends on the loan’s cost, repayment terms, emergency savings and cash flow. Required payments should be protected first. Compare the certain cost of expensive debt with the uncertain outcome of an investment, and seek professional advice when the decision is material.
Final takeaway
Investment is a process of matching money with a future purpose. Start by understanding your cash flow and protecting short-term needs. Then choose products based on time horizon, risk, diversification, costs and current information—not on a promise or a trending tip.
For investor education and current market information, use SEBI’s investor resources. For banking-related notices, check the Reserve Bank of India website. For current tax information, refer to the Income Tax Department portal.
Last reviewed: September 2026
This article is for general educational purposes only. It is not personalised investment, financial, legal or tax advice. Investments can lose value, and rules, fees and product terms may change. Verify current details and consult a qualified professional before making an important financial decision.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Software developer with expertise in full-stack web development and financial market analysis, specializing in building tracking tools for trading metrics.
Comments (0)