Rental Property Investment in India: Yield, Costs and Tenant Management
Learn how to evaluate a rental property in India using net yield, vacancy, legal costs, tenant screening, agreements, maintenance and exit planning.
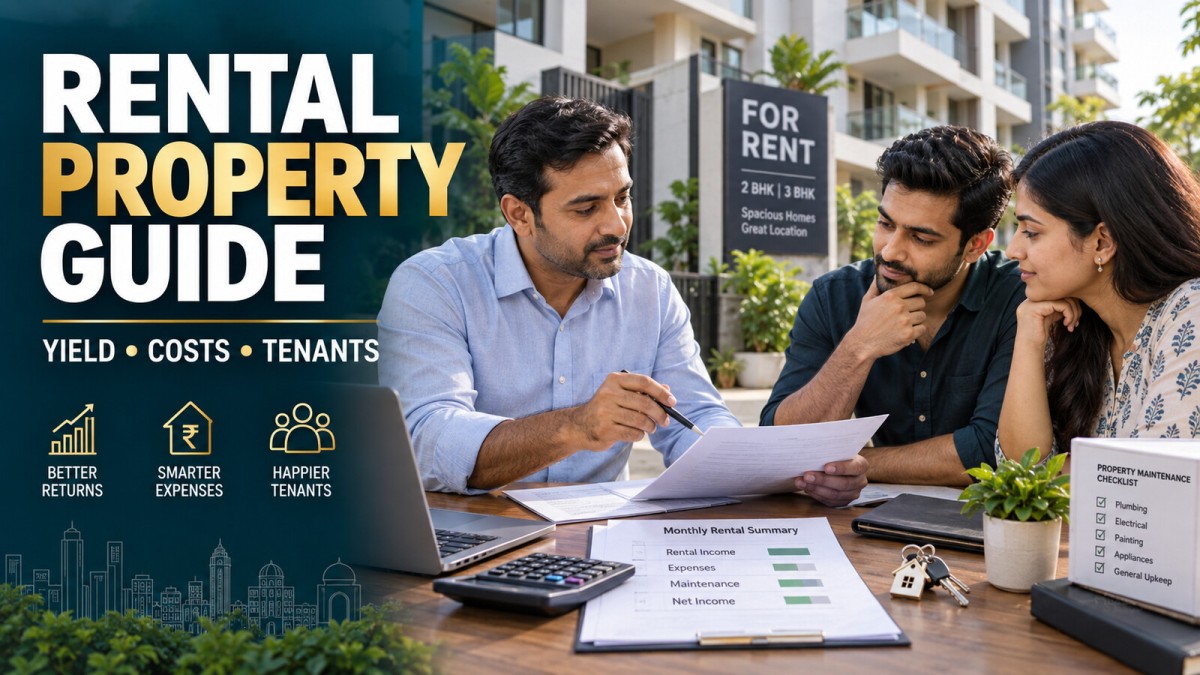
Rental property can look simple from the outside: buy a home, find a tenant and collect rent. In practice, returns depend on purchase price, vacancy, repairs, taxes, financing, tenant quality and the time required to manage the property. A clear cash-flow calculation is more useful than a headline rent figure.
Define the Rental Strategy
Decide whether you want stable long-term rent, furnished accommodation for professionals, student housing or a short-term model where permitted. Each approach has different furnishing, compliance, vacancy and management needs. Choose the tenant demand first and the property second.
Calculate Gross and Net Yield
Gross yield is annual rent divided by purchase price, multiplied by 100. Net yield should subtract vacancy, maintenance, property tax, insurance, repairs, management fees, society charges and other recurring costs. Include one-time rent-ready costs separately.
For illustration, a ₹60 lakh property earning ₹20,000 monthly rent produces ₹2.4 lakh annual gross rent, or 4% gross yield before costs. If a month is vacant and annual expenses total ₹45,000, the net income is lower. This example is only a calculation method, not a return promise.
Study Tenant Demand
Look at employment hubs, colleges, hospitals, transport, daily shopping, safety, parking and internet access. Speak with nearby owners and local brokers about realistic rents, not just advertised asking prices. Compare similar homes with the same furnishing, floor, age and parking conditions.
Inspect and Verify the Property
Check title, ownership, encumbrances, tax receipts, society dues, building permissions and any applicable RERA disclosures. For a resale unit, inspect seepage, plumbing, wiring, appliances and common facilities. If a loan is involved, remember that a lender’s checks are not a substitute for independent legal advice.
Financing and Stress Testing
Calculate the EMI and compare it with conservative net rent. Test a vacancy period, a major repair and a higher interest rate. If the property works only when it is occupied every month and nothing breaks, the plan is fragile. Keep a reserve for several months of property expenses and debt service.
Make the Home Rent-Ready
Set a written budget for painting, locks, lights, fans, plumbing, cleaning, basic furniture and safety improvements. Choose durable materials that are easy to repair. Avoid expensive décor that raises the purchase cost without improving tenant demand or achievable rent.
Set Rent and Screen Tenants Fairly
Use comparable local listings and allow for negotiation. For screening, verify identity and contact details, discuss occupants, employment or income evidence where appropriate, references and the intended stay. Apply the same documented criteria to every applicant and respect privacy.
Use a Written Rental Agreement
The agreement should state rent, due date, deposit, notice period, permitted occupants, repairs, utilities, inspection access, renewal and handover conditions. Follow applicable state rules for registration or police verification. Record the move-in condition with dated photographs and meter readings.
Manage Maintenance and Records
Separate normal wear from tenant-caused damage and respond to urgent plumbing, electrical or safety issues promptly. Keep invoices, rent receipts, deposit records and messages. A simple monthly sheet can track rent received, vacancy, repairs, taxes and net cash flow.
Review the Investment Annually
Once a year, compare actual net income with the original forecast. Check whether rent, insurance, taxes, society charges and repairs have changed. Also compare the property’s current value and liquidity with alternative uses for your capital. A good exit plan is part of a good entry plan.
Common Mistakes
Do not calculate yield using only the seller’s asking rent. Do not ignore vacancy, brokerage, furnishing replacement or legal costs. Do not hand over keys without a signed agreement and documented condition. Do not buy in a weak rental micro-market only because the property looks inexpensive.
Quick Scorecard
- Tenant demand: strong, moderate or uncertain?
- Net yield: calculated after vacancy and recurring costs?
- Legal status: documents independently reviewed?
- Cash buffer: enough for repairs and empty months?
- Management: self-managed or professional support?
- Exit: realistic resale or refinancing route?
Editorial note: This guide is educational, not a guarantee of rental income, appreciation or tax treatment. Verify local tenancy rules, property documents and current tax requirements with qualified professionals.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Software developer with expertise in full-stack web development and financial market analysis, specializing in building tracking tools for trading metrics.
Comments (0)