SIP vs Lump Sum: How to Choose a Mutual Fund Investment Method
Compare SIP and lump-sum mutual fund investing, including timing, risk, rupee-cost averaging, practical scenarios and a clear decision checklist.
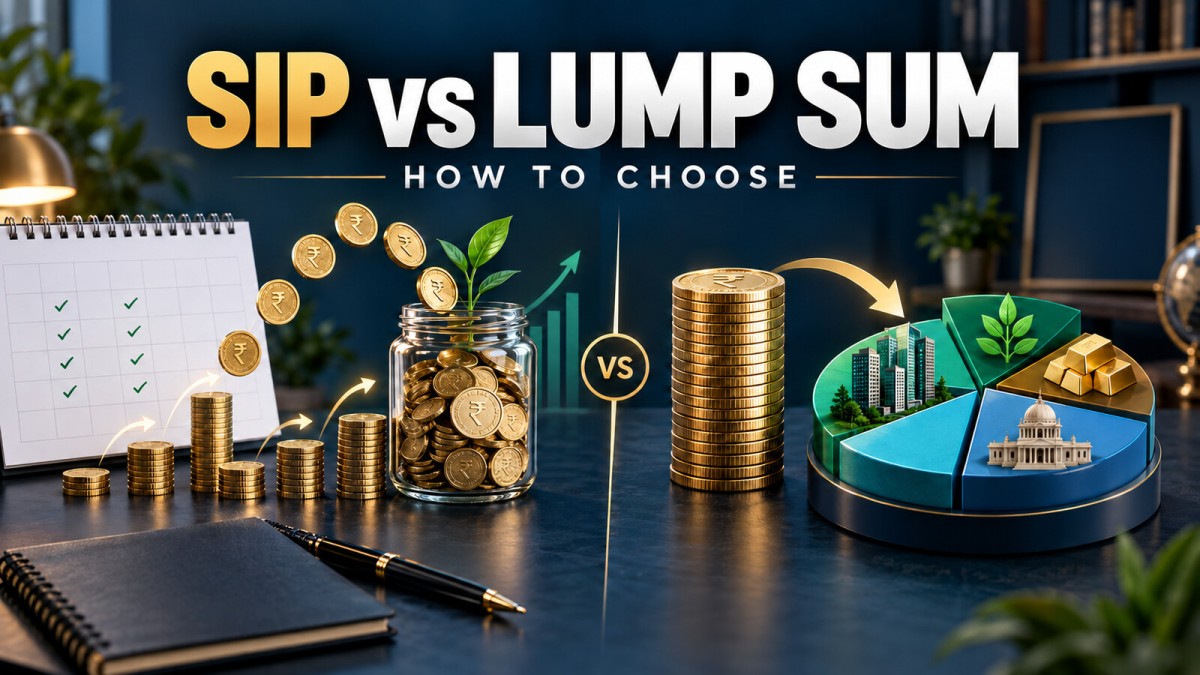
Choosing between a Systematic Investment Plan (SIP) and a lump-sum investment is not about finding one method that is always better. Both are ways of investing in a mutual fund. The right choice depends mainly on when your money becomes available, how stable your cash flow is, your investment horizon and how comfortably you can handle market volatility.
A salaried investor who receives investible income every month may find a SIP natural. Someone who receives a bonus, inheritance or maturity amount may need to decide how to invest money that is already available. This guide explains the trade-offs without promising returns or trying to predict the market.
Quick Answer: SIP or Lump Sum?
- Consider a SIP when money becomes available gradually, you want an automated investing habit, or you are uncomfortable investing a large amount on one date.
- Consider lump sum when the entire amount is already available, your goal is long term, the chosen scheme matches your risk capacity and you can tolerate a fall soon after investing.
- Consider a phased approach when you have a large amount but are not emotionally comfortable investing it at once. Understand that delaying investment also has an opportunity cost.
Before either option, keep suitable emergency funds and address high-cost debt. Money needed soon generally should not be placed in a volatile equity fund merely because SIPs are popular.
What Is a SIP?
A Systematic Investment Plan is an arrangement through which a fixed amount is invested in a mutual fund at regular intervals, commonly every month. Each instalment purchases units at the applicable Net Asset Value (NAV). When the NAV is lower, the same rupee amount buys more units; when it is higher, it buys fewer.
This is often described as rupee-cost averaging. It spreads purchase dates across different market levels, but it does not guarantee a profit or protect an investor from loss. The value of the accumulated units will still move with the underlying portfolio.
Advantages of SIP Investing
- Matches monthly income: investing can happen soon after salary or business income arrives.
- Builds consistency: automation reduces the temptation to postpone investing.
- Spreads entry dates: all units are not purchased at one market level.
- Supports goal planning: the monthly amount can be linked to a long-term target.
- Easy to increase: investors can review and step up contributions as income grows.
Limitations of SIP Investing
- A SIP cannot remove market, credit, interest-rate or liquidity risk.
- Returns are not fixed, and past fund performance does not ensure future results.
- Stopping contributions during a fall can defeat the purpose of disciplined investing.
- If a large amount is already sitting idle, spreading it over a long period may reduce its time in the market.
- A SIP into an unsuitable or expensive scheme remains an unsuitable investment.
What Is a Lump-Sum Investment?
A lump-sum investment means investing a larger amount in one transaction. All units are purchased at the NAV applicable to that transaction. The entire amount therefore begins participating in the market together.
Lump sum is not a separate type of mutual fund. The same scheme may allow both one-time and systematic investments. The difference is the timing of the cash flows.
Advantages of Lump-Sum Investing
- Immediate deployment: money that is already available gets more time invested.
- Simple administration: one transaction is easier to track than many instalments.
- Useful for irregular income: business owners, freelancers or investors receiving a bonus may not have equal monthly surplus.
- No dependence on future contributions: the planned amount is invested at once.
Limitations of Lump-Sum Investing
- The entry date has a larger short-term effect because the full amount is invested at one NAV.
- A decline soon after investing can be emotionally difficult and may lead to panic selling.
- It requires a clear understanding of the goal, time horizon and risk profile.
- Waiting endlessly for the “perfect” entry point can leave money uninvested.
SIP vs Lump Sum: Key Differences
| Factor | SIP | Lump Sum |
|---|---|---|
| Cash flow | Invests smaller amounts regularly | Invests available capital at once |
| Entry timing | Spread across many dates | Concentrated on one date |
| Investor behaviour | Encourages an automated habit | Requires comfort with immediate exposure |
| Time in market | Each instalment has a different holding period | The full amount starts its holding period together |
| Short-term timing impact | Reduced because purchases are staggered | Higher because all units share one entry point |
| Suitable cash pattern | Regular monthly surplus | Bonus, inheritance, asset-sale proceeds or accumulated cash |
| Return guarantee | None | None |
A Fair Comparison Requires Equal Cash Availability
Many online comparisons are misleading because they assume that a SIP investor earns money monthly while a lump-sum investor has the full amount on day one. These are different cash-flow situations.
Suppose Investor A can save ₹10,000 from salary each month. A monthly SIP is a practical way to invest that new surplus. Investor B already has ₹1,20,000 available. For Investor B, comparing an immediate ₹1,20,000 investment with twelve monthly instalments means some cash remains outside the market while waiting to be invested.
If markets rise during that period, immediate investment may benefit from greater time in the market. If markets fall shortly after the first date, staggered purchases may obtain lower average prices. Neither outcome can be known reliably in advance. The decision should therefore be based on the investor’s real cash position and ability to stay invested, not on a back-tested chart selected after the result is known.
How Rupee-Cost Averaging Works
Imagine investing ₹5,000 on three dates when the NAV is ₹50, ₹40 and ₹25. The instalments purchase 100, 125 and 200 units respectively, for a total of 425 units. The total investment is ₹15,000, so the average cost is approximately ₹35.29 per unit.
This example shows how a fixed contribution buys more units at a lower NAV. It does not prove that the final return will be positive. If the NAV remains below the average cost when the investor sells, the investment can still show a loss. Taxes, exit loads and other scheme-specific terms may also affect the amount received.
Which Approach Fits Different Situations?
Regular Salary or Predictable Monthly Income
A SIP often fits because investible money arrives each month. Scheduling the debit shortly after income is credited may make saving easier. The SIP amount should still leave room for essential expenses and emergencies.
Annual Bonus or Large Cash Amount
Lump sum may be reasonable when the goal is distant and the investor accepts volatility. If a sudden decline would cause the investor to exit, a shorter planned deployment schedule may be easier to follow. The temporary parking option and any transfer arrangement should be evaluated for risk, tax and scheme rules.
Short-Term Financial Goal
The main question is not SIP versus lump sum; it is whether the selected asset category is suitable. Equity-oriented funds can be volatile over short periods. Capital needed for fees, a home payment or another near-term commitment may require a lower-risk approach.
Market at a Record High
A market high alone does not reveal what will happen next. Markets can rise further, remain flat or fall. A diversified plan based on goal, allocation and time horizon is more dependable than making an all-or-nothing decision from a headline.
Market Falling Sharply
A decline may allow SIP instalments to buy more units, but continuing is sensible only if the goal, scheme suitability and personal finances remain intact. Do not invest emergency money merely because prices have fallen.
Can You Combine SIP and Lump Sum?
Yes. Investment methods do not have to be mutually exclusive. For example, an investor may continue a regular SIP while investing part of an annual bonus as a lump sum. Another person may divide a large amount into a few planned tranches.
Some investors use a Systematic Transfer Plan (STP), where money is placed in one mutual fund scheme and periodically transferred to another. An STP involves transactions in both schemes and may create tax consequences or exit loads. It is not a risk-free bank instalment and should be understood before use.
Seven Questions to Ask Before Deciding
- When will I need the money? A longer horizon generally provides more time to handle volatility, but no duration guarantees returns.
- Is the money already available? Do not manufacture a lump sum by borrowing, and do not compare future salary with cash available today.
- How much loss can I tolerate? Consider both financial capacity and emotional response.
- Is my emergency fund separate? Unexpected expenses should not force the sale of a volatile investment at a bad time.
- Which asset allocation suits the goal? The equity-debt mix may matter more than the instalment method.
- Have I checked the scheme documents? Review the Riskometer, portfolio, expense ratio, exit load, taxation and investment objective.
- Can I follow the plan during volatility? A theoretically efficient strategy is useless if panic causes you to abandon it.
Common Mistakes to Avoid
- Assuming SIP means guaranteed safety: it spreads purchase timing but does not eliminate losses.
- Selecting a fund only from recent returns: understand its category, risk and role in your portfolio.
- Running too many overlapping SIPs: more schemes do not automatically mean better diversification.
- Ignoring costs and taxes: expense ratios, exit loads and applicable tax rules affect outcomes.
- Using borrowed money: market returns are uncertain while loan repayment is contractual.
- Stopping after a short decline: review the original goal and fund suitability instead of reacting only to price.
- Waiting for certainty: there is no indicator that reliably identifies every market top and bottom.
A Practical Decision Framework
Use this simple sequence:
- Write down the goal, target date and amount.
- Separate emergency and near-term money.
- Choose an asset allocation based on the goal and your risk capacity.
- Select a suitable mutual fund category before selecting the payment method.
- Use SIP for recurring surplus and consider lump sum for capital already available.
- If emotional comfort is a concern, choose a written, limited deployment schedule instead of delaying indefinitely.
- Review periodically, rebalance when necessary and avoid reacting to daily market noise.
Frequently Asked Questions
Does SIP always earn more than lump sum?
No. Results depend on the sequence of market returns, fund performance, investment dates and holding period. SIP and lump sum are contribution methods, not return guarantees.
Is SIP risk-free?
No. A SIP into a market-linked mutual fund carries the risks of that scheme. Staggering purchases may reduce the effect of one entry date, but the value can still fall.
Should I stop my SIP when the market falls?
A fall alone is not a sufficient reason. Review whether the goal, time horizon, asset allocation, fund mandate and your financial situation remain appropriate. Seek qualified advice when needed.
Can I make additional investments while a SIP is active?
Generally, investors can make additional eligible purchases in the same scheme, subject to the fund’s terms. Check the current scheme documents and platform process.
How often should I review my mutual funds?
A planned periodic review is usually more useful than checking daily. Review after major goal, income or family changes, and examine sustained issues rather than reacting to one weak month.
Final Takeaway
SIP is usually convenient for money earned over time; lump sum is a way to deploy money already available. SIP reduces dependence on a single purchase date, while lump sum gives the full capital immediate time in the market. The more important decisions are your goal, emergency preparation, asset allocation, scheme suitability and ability to stay disciplined.
Disclaimer: This article is for general education and does not constitute personalised investment, tax or legal advice. Mutual fund investments are subject to market risks. Read current scheme-related documents, understand applicable costs and taxes, and consider consulting a SEBI-registered investment adviser for advice suited to your circumstances.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Software developer with expertise in full-stack web development and financial market analysis, specializing in building tracking tools for trading metrics.
Comments (0)