How to Build a Monthly Budget in India: 5 Steps You Can Actually Follow
A practical monthly budgeting method for Indian households, covering income, fixed bills, variable spending, savings, debt and a simple monthly review.
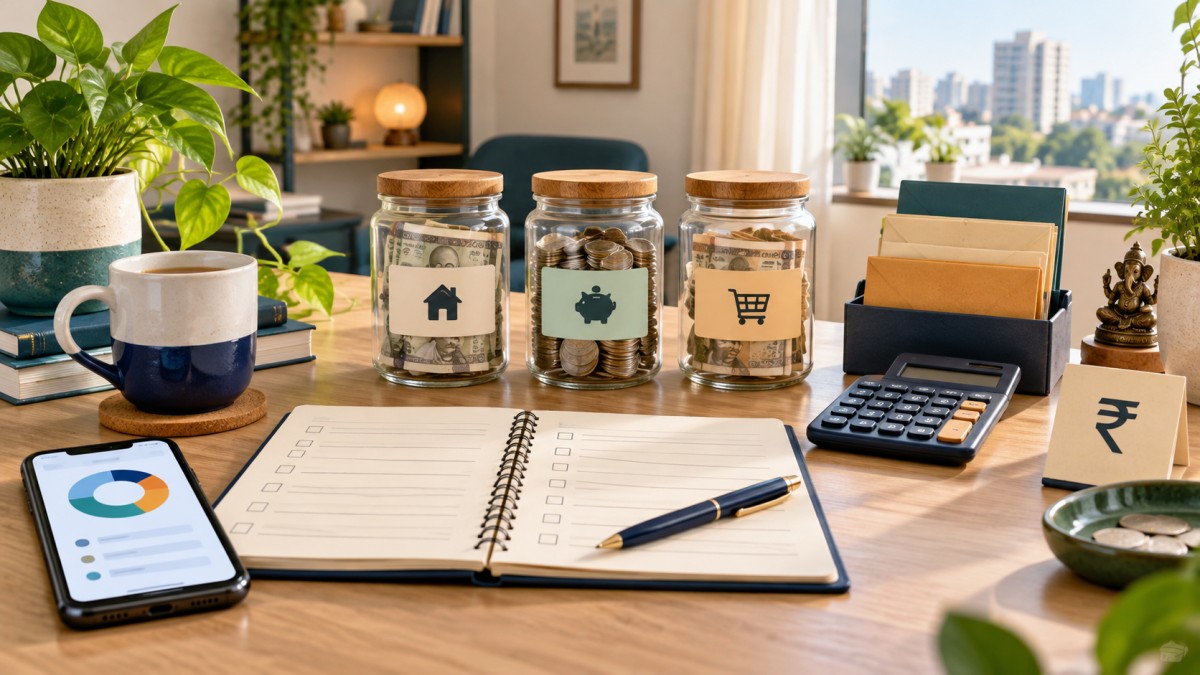
A budget is not a punishment for spending money. It is a simple plan that tells your income where to go before the month gets busy. Without a plan, small UPI payments, food orders, subscriptions and unplanned shopping can quietly use the money meant for bills or savings.
This guide explains a practical way to build a monthly budget in India that can survive real life. It works for a salaried person, a freelancer, a small business owner or a family managing several expenses. The goal is not to copy a perfect percentage. The goal is to create a plan you can understand, review and adjust without giving up after one difficult month.
What is a monthly budget?
A monthly budget is a written estimate of your income and expenses for one month. It normally includes four things: money coming in, essential bills, flexible spending and future goals such as savings or debt repayment.
For example, if your take-home income is ₹50,000, the budget should show how much is needed for rent, groceries, travel, utilities, family commitments, personal spending, savings and unexpected costs. It should also show what happens if an expense is higher than expected. A budget becomes useful when it answers that question before the money is gone.
The five-step method
- Start with your real take-home income.
- List essential and irregular expenses.
- Give flexible spending clear limits.
- Plan savings, debt and future costs.
- Review the budget every week and every month.
Step 1: Start with the income you can actually use
Use the amount that reaches your bank account, not your annual salary package or gross income. If your salary slip includes deductions, loans, insurance or other contributions, the net amount is the number available for the monthly plan.
If your income changes from month to month, do not build the budget around your best month. Use a conservative estimate based on recent income, or create a “minimum income” budget for essential bills and a second plan for extra money. This prevents an unusually good month from turning into a permanent commitment.
For freelancers and business owners, separate personal money from business money as much as possible. Transfer a planned amount to your personal account and keep taxes, business expenses and operating cash outside the household budget. Mixing both accounts makes it difficult to understand what is truly available.
Step 2: Separate essential bills from flexible spending
Essential expenses are the payments that protect your basic living situation or important responsibilities. They may include rent or home-loan payments, electricity, mobile and internet bills, groceries, medicines, school fees, insurance premiums, transport to work and minimum debt payments.
Flexible expenses are still real expenses, but they can usually be reduced, delayed or replaced. Examples include eating out, entertainment, shopping, extra travel, premium subscriptions and some lifestyle purchases.
| Budget group | Examples | How to plan it |
|---|---|---|
| Essentials | Rent, groceries, utilities, medicines | Fund these first and review them for accuracy |
| Flexible spending | Food delivery, shopping, outings | Set a limit instead of trying to predict every rupee |
| Future goals | Emergency fund, education, planned purchase | Move the amount soon after income arrives |
| Debt and obligations | EMI, credit-card balance, family commitments | Record the due date and the full expected payment |
| Irregular costs | Repairs, annual fees, festivals, travel | Save a small amount each month in advance |
Do not hide irregular expenses just because they do not appear every month. A yearly insurance premium, school payment or vehicle service is still part of the real cost of living. Dividing the expected annual amount by twelve gives you a starting monthly provision.
Step 3: Give variable expenses a realistic limit
Most people do not overspend because of one large purchase. They overspend through many small decisions that are hard to see. Review the last 30 to 60 days of bank, card and UPI transactions and group them into broad categories. You do not need twenty-five categories; five to eight useful groups are easier to maintain.
A category limit should be realistic. If you normally spend ₹6,000 on food outside the home, writing ₹500 in the budget may look disciplined but will probably fail. Start with a number you can follow, then reduce it gradually if that is genuinely your goal. A budget that is followed is more valuable than a perfect budget that is ignored.
Weekly limits can make monthly limits easier. If the monthly allowance for flexible spending is ₹8,000, you might divide it into four weekly checkpoints while keeping a small part for the last few days of the month. This is not a strict daily restriction; it is an early warning when spending is moving too quickly.
Step 4: Plan savings, debt and future expenses
Build a small buffer first
An emergency fund is money kept for an unexpected need, such as a medical bill, urgent repair or temporary loss of income. Start with a small reachable target if a large target feels impossible. The first milestone could be one month of essential expenses, followed by a larger reserve over time. Keep this money separate from the account used for daily spending.
Use sinking funds for predictable costs
A sinking fund is a small amount saved regularly for a known future expense. Festival travel, annual insurance, school expenses, a phone replacement or vehicle maintenance may feel like emergencies only because they were not planned. Write down the expected cost and due month, then set aside a monthly portion.
Make debt visible
List each loan or credit-card balance with its minimum payment, due date, interest or charges where known, and outstanding amount. Pay at least the required amount on time, then choose a repayment priority that fits your situation. High-cost debt deserves careful attention, but do not stop essential bills or emergency protection without understanding the consequences.
Do not treat a credit-card limit as income. A purchase becomes affordable only when the full repayment fits inside the budget, not when the card can technically approve it.
Choose a savings amount you can maintain
The popular 50/30/20 split can be a useful starting idea, but it is not a law. Rent, family responsibilities, city, income and debt can make those percentages unsuitable. Use the principle behind it—separate needs, wants and future goals—then choose numbers that match your life.
Step 5: Review the plan before it becomes a problem
Spend ten minutes once a week checking the main categories. Look for bills due soon, unusual payments and categories that are running ahead of plan. A weekly check is enough to make a small correction; waiting until the final day of the month usually leaves no room to adjust.
At the end of the month, compare the plan with what actually happened. Ask:
- Which expense was higher than expected, and why?
- Which subscription or purchase no longer provides enough value?
- Were irregular expenses included or forgotten?
- Did the savings transfer happen at the planned time?
- What single change would make next month easier?
Do not label the whole budget a failure because one category went over. Move money from a lower-priority category if possible, record the reason, and improve the next month’s estimate. A budget is a feedback system, not a test that you pass only when every number is exact.
A simple example for a ₹60,000 monthly income
Imagine a person receives ₹60,000 after deductions. Their first draft might look like this:
| Area | Example amount | Purpose |
|---|---|---|
| Essential household costs | ₹32,000 | Rent, groceries, utilities, travel and medicines |
| Flexible spending | ₹12,000 | Eating out, personal purchases and entertainment |
| Savings and planned goals | ₹10,000 | Emergency fund or a defined future goal |
| Irregular-cost buffer | ₹6,000 | Repairs, annual payments or a family need |
This is only an illustration, not a recommended formula. Another person may have a higher rent, a larger EMI, lower travel costs or family responsibilities. The important feature is that every rupee has a job and the plan includes a buffer instead of assuming that nothing unexpected will happen.
Budgeting when income is irregular
Variable income needs a different order of priority. First cover essential expenses and minimum obligations using a conservative income number. When extra income arrives, divide it deliberately between taxes or business needs, emergency savings, debt repayment and a limited amount of lifestyle spending.
A separate “income holding” account can help freelancers and commission-based workers. Money can remain there until the next monthly transfer is decided. This reduces the temptation to spend a large payment immediately and then struggle during a quiet period.
Budgeting for couples and families
Money conversations become easier when the household agrees on shared responsibilities rather than judging individual purchases. Write down which bills are joint, which expenses are personal and which goals matter to everyone. A shared spreadsheet or monthly check-in can provide visibility without requiring every small purchase to be approved.
For children’s expenses, medical needs and family support, use a range instead of pretending that every month will be identical. If an amount varies, budget for a normal level and keep a separate buffer for higher months.
Should you use an app, spreadsheet or notebook?
The best tool is the one you will open regularly. A spreadsheet makes categories and monthly comparisons easy. A budgeting app can save time if it connects to accounts safely and gives you clear control over your data. A notebook can work well for a simple cash-based plan.
Do not share banking passwords, card PINs, OTPs or recovery codes with a budgeting service or another person. Check the privacy, security and access settings of any financial app before connecting an account. If you prefer manual entry, a weekly ten-minute update is usually enough.
Common budgeting mistakes
- Making the plan too strict: removing every enjoyable expense often causes a rebound.
- Using gross income: the budget must use the amount actually available after deductions.
- Forgetting annual costs: predictable yearly payments should be divided into monthly provisions.
- Ignoring small digital payments: UPI and one-click purchases still need a category.
- Counting borrowed money as income: a credit limit or loan is not monthly earnings.
- Copying another person’s percentages: a plan must reflect your rent, family and goals.
- Quitting after one bad month: update the estimate and continue; do not throw away the system.
Frequently asked questions
What is the easiest budget rule for a beginner?
Start with four groups: essentials, flexible spending, future goals and irregular costs. Track those groups for one month before adding more detail. Simplicity makes it more likely that you will keep going.
How much of my salary should I save?
There is no single percentage that fits every household. Save a consistent amount that does not force you to miss essential bills, then increase it when your income or expenses allow. Building the habit and protecting an emergency buffer are more important than copying a popular ratio.
How can I control UPI and small daily spending?
Review the transaction history once a week and group small payments into a visible category such as snacks, transport or food delivery. Use a weekly spending limit and remove saved cards or unnecessary subscriptions if convenience is causing repeated purchases.
Should I pay debt or build an emergency fund first?
Many people need both: keep a small emergency cushion so an unexpected bill does not create new debt, while making required debt payments on time. The right balance depends on interest costs, income stability and the type of debt.
Is a budget necessary if I earn a good salary?
Higher income can make mistakes less urgent, but it does not automatically create savings. A clear plan helps prevent lifestyle costs from expanding with income and makes larger goals easier to fund.
Can I make a budget with cash only?
Yes. Cash envelopes, a notebook or a simple spreadsheet can work. The method matters less than recording the starting amount, setting limits and checking what remains.
What should I do when I overspend?
Stop and identify the reason without hiding the transaction. Reduce a lower-priority category, use the buffer if one exists, and update next month’s estimate. Avoid using a new loan or credit purchase to make the budget appear balanced.
Final takeaway
A useful monthly budget is a small, honest plan—not a collection of unrealistic restrictions. Begin with take-home income, protect essential expenses, give flexible spending a limit, save for predictable costs and review the numbers regularly. Your first version will not be perfect, and it does not need to be. It needs to be clear enough to use and flexible enough to improve.
For current information about banking notices and financial education, refer to the Reserve Bank of India website. For tax-related information, check the current guidance on the Income Tax Department portal.
Last reviewed: September 2026
This article is for general educational purposes only. It is not personalised financial, investment, legal or tax advice. Your circumstances may be different; check current rules and speak with a qualified professional before making an important financial decision.
Frequently Asked Questions
What's Your Reaction?
 Like
1
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Software developer with expertise in full-stack web development and financial market analysis, specializing in building tracking tools for trading metrics.
Comments (0)