Personal Finance: A Practical Beginner Guide to Managing Money
Learn how to manage income, spending, emergency savings, debt, insurance and investments with a realistic personal-finance plan and simple monthly routine.
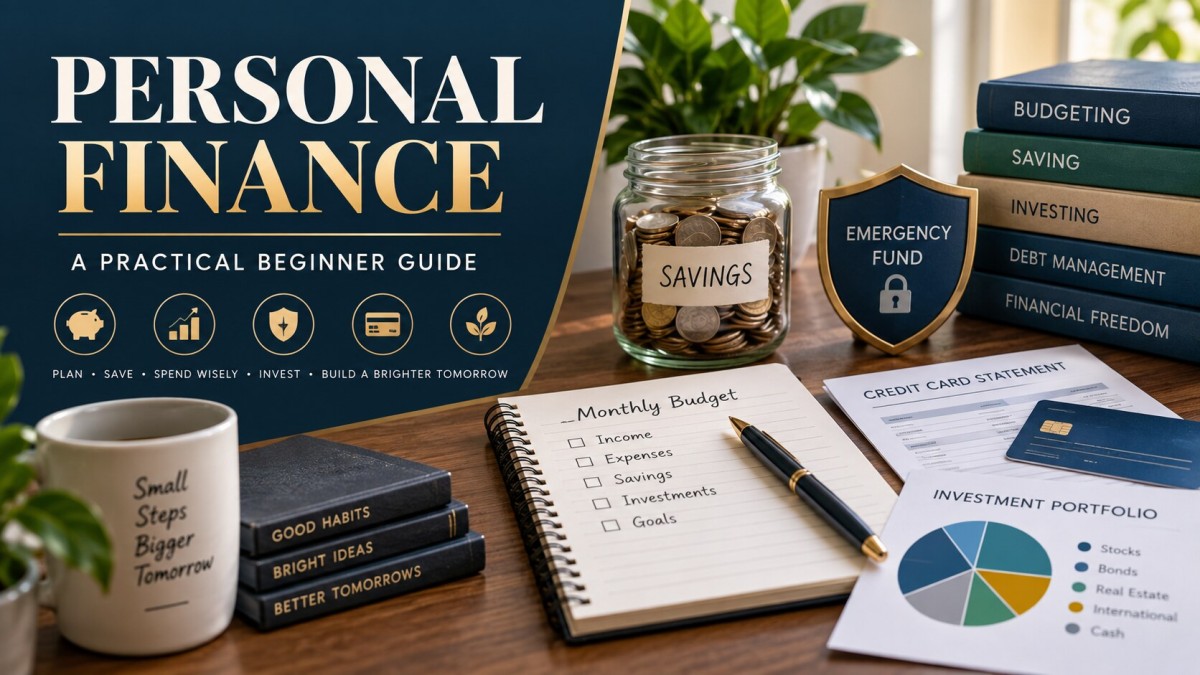
Personal finance is the way you plan and manage income, spending, savings, debt, insurance and investments. It is not only about earning more. A reliable plan helps you use today’s money while preparing for emergencies and future goals.
Begin with a clear picture
List monthly take-home income, essential expenses, discretionary spending, debts, savings and investments. Review several months of bank and payment records because estimates often miss subscriptions, fees and irregular purchases.
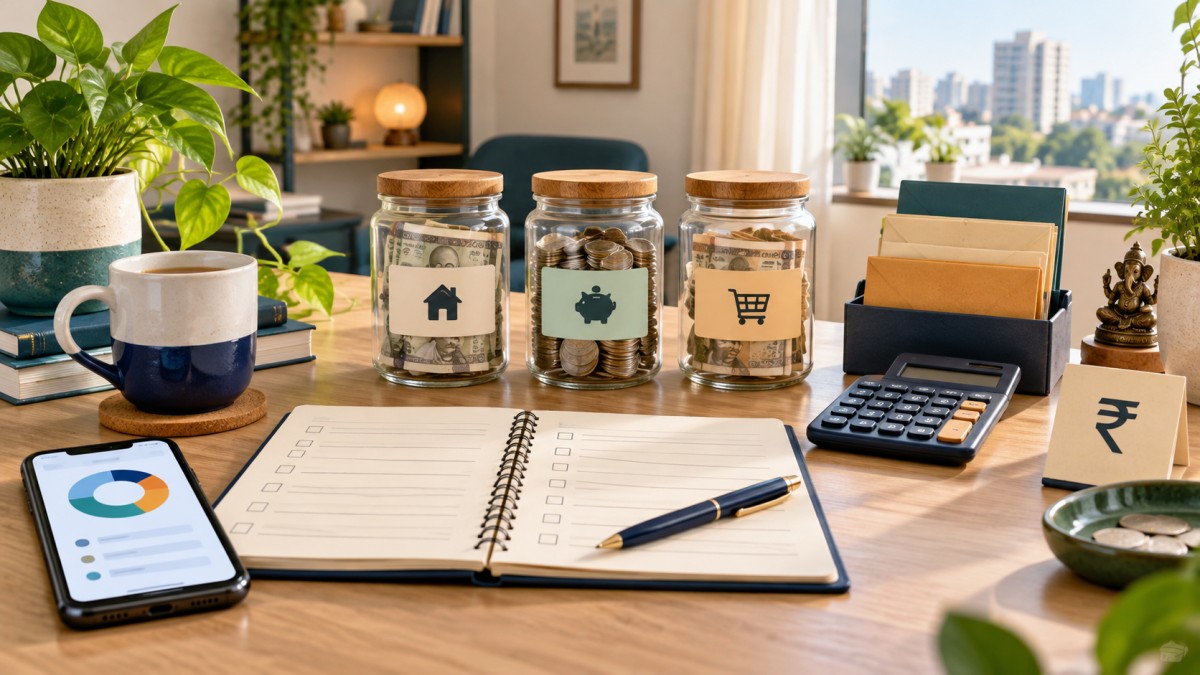
Create a realistic budget
A budget gives every rupee a purpose without requiring a perfect formula. Start with essentials, debt obligations and important goals. Set a reasonable amount for flexible spending so the plan can be followed consistently. Compare actual spending with the plan at month-end and adjust.
Build an emergency fund
Emergency savings are for genuine surprises such as urgent repairs, temporary income loss or medical costs not covered elsewhere. Keep this money accessible and separate from routine spending. Build it gradually; the suitable amount depends on job stability, dependants, insurance and monthly obligations.
Manage debt carefully
Record each balance, interest rate, EMI and due date. Pay at least the required amount on time and prioritise expensive debt according to a practical repayment plan. Avoid using new credit to hide an unaffordable monthly gap.
Protect against major risks
Health, life, motor and property insurance can reduce the financial impact of specific events, subject to policy terms. Compare coverage, exclusions, waiting periods, deductibles and claim procedures—not only premium. Life cover is especially relevant when others depend on your income.
Save and invest for goals
Separate short-term goals from long-term goals. Money needed soon generally requires greater stability and liquidity, while longer horizons may allow market-linked investments according to risk capacity. Diversification can reduce dependence on one asset, but it cannot eliminate loss.
Useful financial goals
- Emergency reserve
- Debt repayment
- Education or skill development
- Home or vehicle purchase
- Retirement planning
- Family protection and insurance
A simple monthly routine
- Check income and all upcoming bills.
- Transfer savings soon after income arrives.
- Review bank, card and wallet statements.
- Track debt balances and due dates.
- Check progress toward one or two priority goals.
- Store important documents and update nominees where appropriate.
Common mistakes to avoid
- Budgeting from memory instead of actual records.
- Investing before creating emergency savings.
- Confusing insurance with guaranteed investment returns.
- Ignoring small recurring charges.
- Taking high-cost debt for lifestyle spending.
- Following online tips without checking risk, fees and suitability.
A practical 30-day starting plan
During week one, collect records and calculate your monthly baseline. In week two, cancel unused subscriptions and set bill reminders. In week three, start an automatic emergency-fund transfer. In week four, review debt and write one short-term and one long-term goal with a target date.
Frequently asked questions
Do I need a large income to manage money well?
No. Income affects the pace of progress, but tracking, prioritising and avoiding expensive mistakes are useful at every income level.
Should I save or repay debt first?
Keep a basic emergency buffer while addressing expensive debt. The right balance depends on interest rates, income stability and essential obligations.
How often should I review my plan?
A short monthly review is useful, plus a deeper review after a major change such as a new job, loan, marriage or child.
Final takeaway
Good personal finance is built through repeatable habits: spend with awareness, maintain emergency savings, use debt carefully, protect important risks and invest according to clear goals. A simple plan followed consistently is more valuable than a complicated plan that is ignored.
Disclaimer: This article is for general educational information only and is not personalised financial, investment, insurance, tax or legal advice. Verify current rules and consult qualified professionals when needed.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Software developer with expertise in full-stack web development and financial market analysis, specializing in building tracking tools for trading metrics.
Comments (0)