Investment Strategies for Beginners: A Practical Step-by-Step Guide
Learn how to start investing with clear goals, an emergency fund, suitable asset allocation, diversification, cost awareness and a practical 30-day plan.
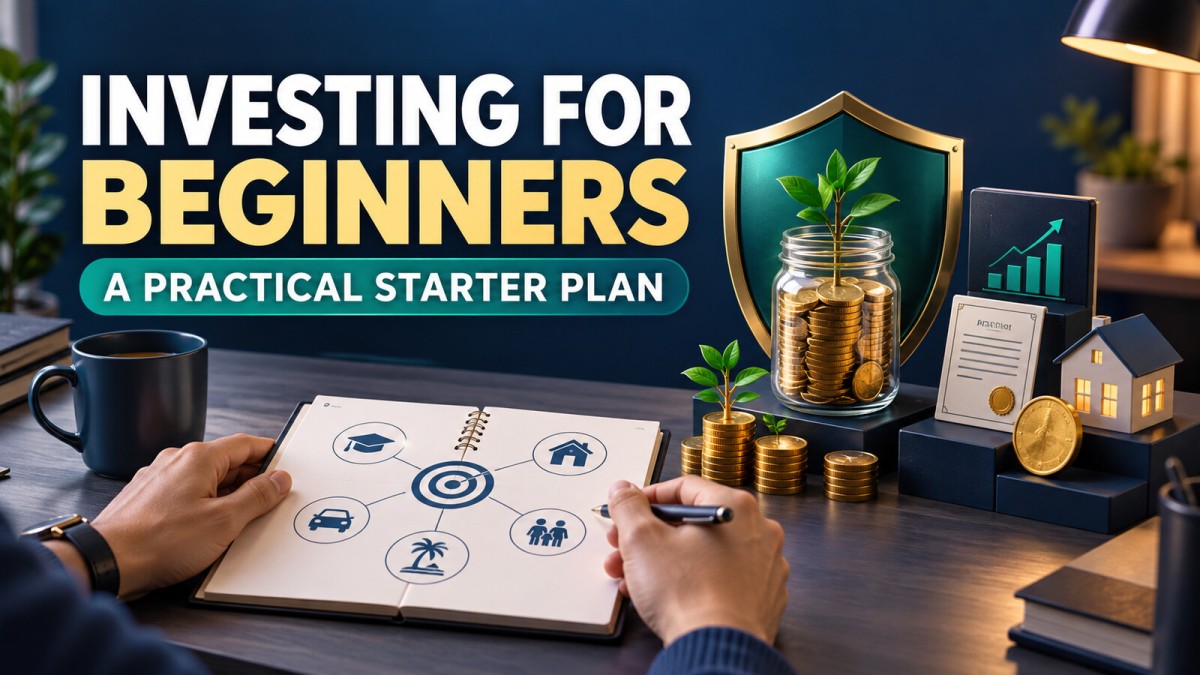
Investing can help turn today’s savings into money for future goals, but beginners are often pushed toward products before they have a plan. A better starting point is to understand your cash flow, protect yourself from emergencies, define your goals and then choose investments that match the time available and the amount of risk you can genuinely handle.
This guide presents a practical sequence for an Indian beginner. It does not promise quick wealth or recommend a particular stock, mutual fund or platform. Its purpose is to help you build a repeatable decision-making process.
Step 1: Build a Financial Base Before Investing
Investing should not make everyday finances fragile. Before putting substantial money into market-linked products, review these foundations:
- Track cash flow: know your monthly income, essential expenses, debt payments and realistic surplus.
- Create an emergency reserve: keep accessible money for job loss, medical needs, repairs and other surprises.
- Address expensive debt: guaranteed interest on high-cost debt can outweigh uncertain investment returns.
- Maintain suitable insurance: health insurance and, where dependants rely on your income, appropriate life cover protect the plan from major shocks.
The right emergency-fund size differs by household. Income stability, dependants, health needs and access to support matter more than copying a fixed number from social media.
Step 2: Turn Wishes into Clear Financial Goals
“I want to build wealth” is too broad to guide an investment. A useful goal identifies the purpose, current estimated cost, target date and amount you can contribute.
| Goal type | Typical concern | Planning priority |
|---|---|---|
| Near term | Money may be needed soon | Capital stability and easy access |
| Medium term | Some growth is needed, but large falls may disrupt the goal | Balanced risk and flexibility |
| Long term | Inflation can significantly increase the future cost | Growth potential with tolerance for volatility |
A wedding next year, a home purchase after several years and retirement decades away should not automatically use the same investment mix. The goal’s deadline determines how much uncertainty it can tolerate.
Step 3: Understand Risk Beyond “Profit and Loss”
Risk is not limited to a price falling on a screen. Beginners should understand several types:
- Market risk: prices can decline because of economic, business or investor conditions.
- Credit risk: a borrower or bond issuer may fail to meet an obligation.
- Interest-rate risk: changes in rates can affect bond prices and borrowing conditions.
- Liquidity risk: an investment may be difficult to sell quickly at a fair price.
- Inflation risk: money may grow too slowly to maintain purchasing power.
- Concentration risk: too much exposure to one company, sector, asset or country can magnify losses.
- Behaviour risk: fear, greed and overconfidence can lead to buying high or selling low.
Your risk capacity is the financial loss your goal can withstand. Your risk tolerance is how calmly you can handle volatility. A plan must respect both.
Step 4: Learn the Main Investment Building Blocks
Cash and Deposits
Bank balances and deposits can support emergencies and near-term goals. They are generally easier to understand than market-linked assets, but their returns may not always outpace inflation after tax. Check institution limits, access conditions and premature-withdrawal rules.
Bonds and Debt Investments
Debt instruments involve lending money to a government, company or other issuer. They may offer more predictable cash flows than equities, but they are not automatically risk-free. Credit quality, maturity, interest-rate sensitivity, liquidity and costs matter.
Equity
Equity represents ownership in a business. It can provide long-term growth, but prices can fluctuate sharply and individual companies can permanently lose value. Direct stock selection requires research into the business, financial statements, competition, valuation and governance.
Mutual Funds and Exchange-Traded Funds
Pooled funds allow investors to hold a portfolio through one product. Categories differ widely in objective, asset mix, risk, cost and taxation. A fund should be chosen for its role in the plan, not only because it recently produced a high return. Read current scheme documents and the Riskometer before investing.
Gold
Gold may diversify a portfolio and behave differently from equities in some periods. It does not generate business earnings, and its price can also fall. Jewellery includes making charges and is primarily a consumption purchase rather than an efficient investment format.
Real Estate
Property may provide use, rental income or appreciation, but it usually requires large capital. Transaction costs, legal checks, maintenance, taxes, vacancy and low liquidity must be considered. One property can also create heavy concentration in a single location.
Retirement and Government-Backed Schemes
India offers retirement and long-term savings arrangements with different eligibility, lock-ins, tax treatment and investment rules. These terms can change. Verify current information on the relevant regulator or official scheme website rather than relying on an old chart.
Step 5: Use Asset Allocation as the Core Strategy
Asset allocation means dividing money among categories such as equity, debt, cash and gold. It is one of the most important portfolio decisions because each asset behaves differently.
An investor with a distant goal and stable finances may be able to hold more growth assets. Someone approaching a fixed deadline may need a larger allocation to comparatively stable assets. There is no universal “best” percentage.
A simple allocation that you understand and can maintain is often more useful than a complicated portfolio of overlapping products. Diversification reduces dependence on a single outcome, but it cannot eliminate market loss.
Step 6: Decide Between SIP and Lump Sum
A Systematic Investment Plan (SIP) invests a fixed amount at regular intervals. It suits money that becomes available monthly and can help automate discipline. A lump-sum investment deploys available capital in one transaction.
SIP spreads purchase dates but does not guarantee profit. Lump sum gives the full amount immediate time in the market but makes the entry date more significant in the short run. Choose based on actual cash availability, horizon and behaviour—not on an attempt to predict every market move.
Step 7: Keep Costs, Taxes and Liquidity Visible
Headline returns do not equal the amount an investor keeps. Depending on the product, outcomes may be affected by:
- Expense ratios or management charges
- Brokerage and transaction charges
- Exit loads or early-withdrawal penalties
- Bid-ask spreads
- Account or platform fees
- Applicable taxes
Tax rules and product terms change, so check current official information before acting. Also ask how quickly money can be accessed and whether selling during a difficult market could damage the goal.
Step 8: Choose a Safe and Regulated Route
Before opening an account or paying anyone, verify the entity’s registration and contact details through the appropriate regulator. Use official websites and applications, enable multi-factor authentication and never share an OTP, PIN, password or screen-control access.
Be cautious when someone:
- Promises guaranteed or unusually high returns
- Creates pressure to invest immediately
- Requests payment to a personal account
- Claims that risk does not exist
- Shows screenshots instead of verifiable records
- Asks for login credentials, OTPs or remote access
- Sells tips through an unverified social-media group
If you need personalised advice, verify that the professional is appropriately registered. A popular content creator is not automatically qualified to evaluate your finances.
Step 9: Start Simple and Automate
Beginners sometimes collect many funds and stocks because each appears to offer diversification. In reality, several products may own the same underlying assets. Complexity makes monitoring harder and can hide costs.
Start with a small number of understandable holdings linked to specific goals. Automate regular contributions if that supports your cash flow. Increase the contribution when income rises, but do not commit an amount that forces frequent withdrawals.
Step 10: Review and Rebalance—Do Not Constantly React
A portfolio needs review, not continuous interference. A useful review asks:
- Has the goal or target date changed?
- Has income, debt, health or family responsibility changed?
- Has the asset allocation moved far from the plan?
- Is a product still following its stated objective?
- Are costs, risk and taxation still understood?
- Is there unnecessary duplication?
Rebalancing restores the chosen allocation by directing new money or buying and selling assets. Selling may involve tax or charges, so evaluate the consequences. Do not replace a sound investment only because it underperformed for a short period.
A Beginner Portfolio Process—Not a Model Portfolio
Instead of copying a percentage allocation, follow this sequence:
- List each financial goal and its deadline.
- Separate emergency and near-term money.
- Assess risk capacity and tolerance.
- Choose an asset mix for each goal.
- Select simple, regulated products that fit that mix.
- Document why each holding exists.
- Automate contributions where practical.
- Review on a planned schedule and after major life changes.
This process remains useful even when products, market conditions and tax rules change.
Common Beginner Mistakes
- Investing without an emergency reserve: an unexpected bill may force a sale at the wrong time.
- Chasing recent winners: last year’s best-performing asset can disappoint later.
- Confusing volatility with fraud: legitimate investments can fluctuate, while scams often hide risk with smooth promises.
- Borrowing to invest: investment returns are uncertain but loan repayments are compulsory.
- Ignoring inflation: a future goal may cost much more than its price today.
- Overtrading: frequent activity can increase cost, tax and emotional mistakes.
- Depending on one asset: a single stock, property or sector can expose the plan to avoidable concentration.
- Checking daily: short-term noise can push a long-term investor away from a reasonable plan.
A 30-Day Starter Plan
Week 1: Organise
Calculate income, essential expenses, debt obligations and available savings. List insurance policies, accounts and existing investments.
Week 2: Define Goals
Write the purpose, target date and estimated amount for each goal. Separate near-term commitments from long-term goals.
Week 3: Learn and Verify
Study the basic differences among cash, debt, equity, pooled funds, gold and property. Verify providers and read product documents before opening or funding an account.
Week 4: Implement a Small Plan
Choose an affordable contribution, set up a simple tracking sheet and write review rules. A small plan that continues is better than an aggressive plan abandoned after one difficult month.
Frequently Asked Questions
How much money is needed to start investing?
Minimum amounts vary by product and provider. More important than starting with a large amount is ensuring that the contribution is affordable, the product is understood and emergency money remains available.
Should a beginner invest directly in stocks?
Direct stocks require business research, diversification and the ability to tolerate company-specific losses. A beginner should first understand these demands and compare them with diversified alternatives.
Are mutual funds guaranteed?
No. Mutual fund values depend on their underlying assets and are subject to scheme-specific risks. Review the investment objective, Riskometer, costs and documents.
What is the best investment for everyone?
There is none. Suitability depends on the goal, time horizon, liquidity needs, tax position and risk capacity. A product can be appropriate for one goal and unsuitable for another.
When should I change an investment?
Consider change when the goal, allocation or product suitability changes, or when there is a sustained problem with mandate, cost or quality. Avoid switching only because of short-term performance rankings.
Final Takeaway
A strong beginner investment strategy is usually less exciting than online marketing suggests. Build a financial base, define goals, understand risk, diversify, control costs, use regulated channels and follow a review schedule. Wealth building is uncertain and rarely smooth, but a clear process can help you make more consistent decisions.
Disclaimer: This article provides general educational information and is not personalised investment, tax, insurance or legal advice. Investments can lose value. Product rules and tax treatment may change. Read current official documents and consider consulting a SEBI-registered investment adviser for guidance suited to your circumstances.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Software developer with expertise in full-stack web development and financial market analysis, specializing in building tracking tools for trading metrics.
Comments (0)