Financial Planning for Freelance Developers: Manage Income, Taxes and Savings
A practical financial planning guide for freelance web and mobile developers, covering irregular income, business expenses, taxes, emergency savings, insurance and long-term goals.
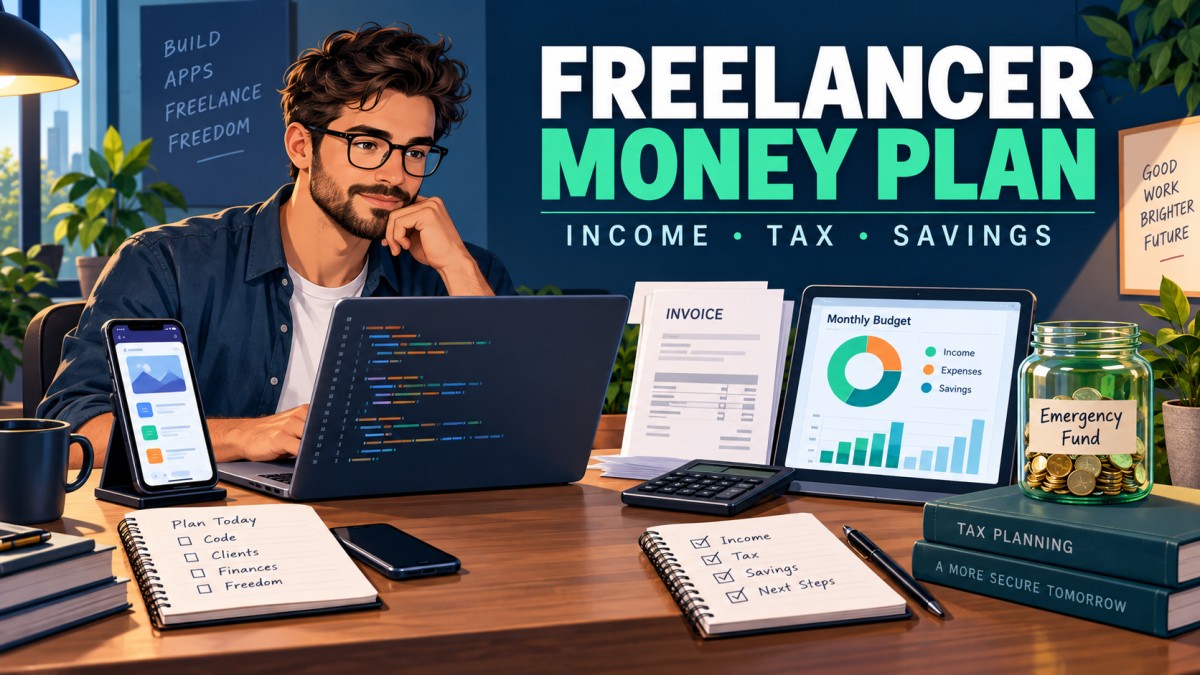
Freelancing gives developers freedom to choose projects and work from almost anywhere. It also changes the way money must be managed. A monthly salary arrives on a predictable date, while freelance income may arrive in different amounts and at different times. Good financial planning creates stability around that uncertainty.
This guide focuses on practical habits for independent web and mobile developers. It is educational information, not personalised financial or tax advice.
Why Freelancers Need a Different Money System
A freelancer often acts as both employee and business owner. Client payments may be delayed, software subscriptions renew automatically, and taxes or professional expenses can arrive months after the income was earned. Personal and business money can also become mixed in one account, making it difficult to know what is truly available to spend.
1. Separate Business and Personal Money
Use a dedicated bank account for client payments and work-related expenses wherever practical. Pay yourself a planned monthly amount into your personal account instead of spending directly from every incoming payment. This creates a clear record and reduces the temptation to treat a large invoice as permanent income.
Keep invoices, receipts, contracts and payment confirmations organised by month. A simple folder structure and consistent filenames can save hours during tax preparation.
2. Build a Freelancer Budget
Start with your lowest realistic monthly income, not your best month. List essential personal costs such as rent, groceries, utilities, transport, debt payments and family commitments. Add business costs such as hosting, domains, software, equipment, internet and professional services.
Then create separate categories for taxes, emergency savings, long-term goals and flexible spending. A budget should be realistic enough to follow during a slow month; an extreme plan usually fails when work becomes busy or income changes.
3. Use an Income Allocation Rule
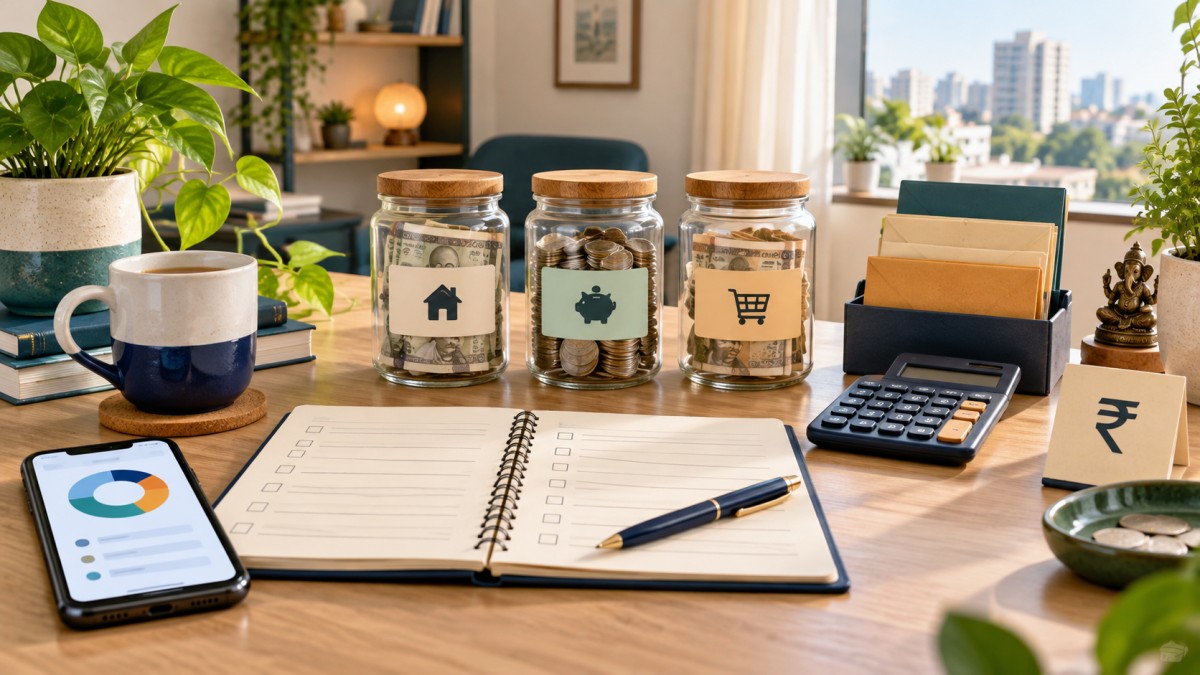
Whenever a client payment arrives, divide it into labelled buckets. One bucket can cover near-term living costs, another can hold the estimated tax amount, and others can fund business expenses, emergency savings and long-term goals. The exact percentages depend on your location, income, deductions and responsibilities.
Keep the tax bucket separate and do not treat it as spare cash. A qualified tax professional can help you estimate advance payments and eligible business expenses under the rules that apply to you.
4. Create a Cash-Flow Calendar
Record expected invoice dates, payment terms, recurring subscriptions, loan instalments and annual renewals. Mark invoices as sent, due, received or overdue. This makes gaps visible before they become emergencies.
For new clients, use a written scope, milestone payments and a clear due date. Deposits or staged billing can reduce the risk of completing a large project before receiving any payment.
5. Build an Emergency Fund
Freelancers benefit from a larger cash buffer because work and payments are less predictable. Begin with a small target, then work toward several months of essential personal and business expenses. Keep this money accessible and separate from high-risk investments.
Use the fund for genuine disruptions such as a health issue, client delay, equipment failure or sudden loss of work. Refill it after using it before increasing optional spending.
6. Plan for Taxes Carefully
Tax treatment depends on your country, business structure, income type and deductible expenses. Keep records throughout the year rather than trying to reconstruct everything at the deadline. Save invoices for equipment, software, internet and professional services only when they are genuinely connected to your work and permitted under local rules.
Do not copy a tax strategy from another developer without checking whether it applies to you. Ask a qualified local professional about registration, invoicing, advance tax, GST or other obligations relevant to your situation.
7. Protect Your Ability to Earn
Your skills and working time are often your biggest financial assets. Consider appropriate health insurance, equipment cover and professional liability protection where relevant. Maintain secure backups of code and client deliverables, use two-factor authentication and keep recovery details safe.
Insurance terms differ widely. Compare exclusions, waiting periods, limits and claim requirements instead of choosing only by the lowest premium.
8. Manage Irregular Client Income
Do not increase your fixed lifestyle costs every time you have a strong month. Treat unusually large payments as an opportunity to strengthen the emergency fund, pay necessary business costs or advance a long-term goal.
Maintain a client pipeline even when you are busy. Follow up on proposals, ask for referrals and keep a record of payment reliability. A client who pays late can create more financial stress than a client with a slightly lower rate who pays on time.
9. Save and Invest for Long-Term Goals
First stabilise cash flow, clear expensive debt and build an emergency reserve. Only then decide how much can be invested for long-term goals. Match the product and risk level to the time horizon, and diversify rather than depending on one asset or one market.
Retirement planning is especially important for freelancers because there may be no employer contribution. Review nominees, beneficiaries, fees, taxes and access rules before choosing a product.
10. Review Your Finances Monthly
- Compare money received with invoices expected.
- Move the planned tax amount into its separate bucket.
- Check business subscriptions and cancel unused services.
- Review overdue invoices and follow up professionally.
- Update the emergency-fund and long-term-goal totals.
- Check whether next month’s essential costs are covered.
Common Mistakes Developers Make
- Spending gross invoice income as if it were take-home pay
- Mixing client money with personal money
- Ignoring late payments and unclear contracts
- Buying equipment on impulse during a strong month
- Investing before building a cash buffer
- Forgetting annual renewals and tax deadlines
- Relying on one client for most income without a backup plan
Simple Freelancer Finance Checklist
Use a separate business account, track every invoice, keep a tax reserve, budget from a conservative income number, build an emergency fund, protect your health and equipment, and review the system each month. The goal is not to predict every payment. It is to make the next decision clear even when income changes.
Frequently Asked Questions
How much should a freelancer save for taxes?
There is no single percentage for everyone. It depends on local rules, business structure, deductions and total income. Keep a separate reserve and confirm the estimate with a qualified local tax professional.
Should freelancers invest every month?
Regular investing can be useful, but stability comes first. Build emergency savings and manage costly debt before committing to a plan you may need to interrupt.
What if a client pays late?
Follow the contract, send a polite written reminder, confirm the invoice details and document communication. Improve future contracts with milestones, deposits and late-payment terms where legally appropriate.
Final Thoughts
Freelance income becomes easier to manage when every payment has a job. Separate business and personal money, reserve for taxes, protect your ability to work and build savings before taking unnecessary risk. A simple repeatable system can give independent developers more confidence and flexibility.
Disclaimer: This article is for general education and does not replace personalised financial, investment, insurance or tax advice. Rules and product terms vary by location and can change. Consult a qualified professional before making decisions.
Frequently Asked Questions
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Wow
0
 Sad
0
 Angry
0
Software developer with expertise in full-stack web development and financial market analysis, specializing in building tracking tools for trading metrics.
Comments (0)